aab.uz

General terms
Loan target
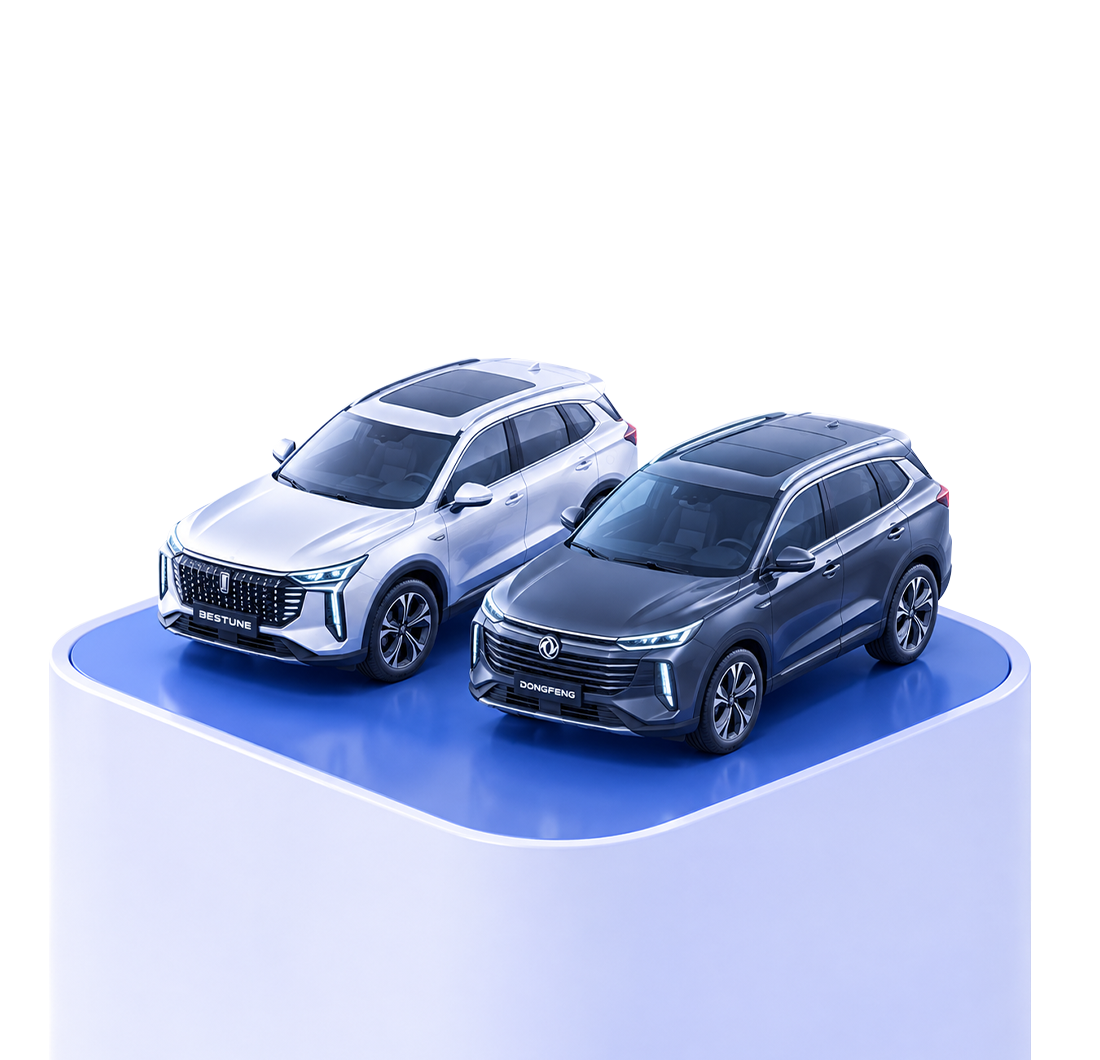
Purchase of motor vehicles of BAW, BESTUNE, DONGFENG, SHINERAY and other brands supplied by AUTOCENTER LLC, LUXEMOTORS LLC, RADOR AUTO LLC, and their authorized dealers.
Loan currency
soum
Loan amount
for legal entities - up to 5 billion soums, for individual entrepreneurs - up to 3 billion soums
Interest rate
from 0% to 19% per annum
Credit term
up to 60 months
Loan processing method
bank branch
Form of issue
non-cash
Collateral
Motor vehicles purchased with loan proceeds shall be accepted as collateral at a value not exceeding 70% of their contractual purchase price. The remaining portion of the required collateral shall be covered by a loan non-repayment risk insurance policy issued by an insurance company whose insurance terms are acceptable to the Bank, or by a third-party guarantee. In the interim, a third-party guarantee may be provided as temporary security for the loan principal obligation until the vehicle is formally pledged as collateral. Third-party guarantees shall be accepted in accordance with the requirements of the “Procedure for Accepting Collateral to Secure the Fulfilment of Customers’ Obligations under Credit Facilities at Asia Alliance Bank JSCB.”
Grace period
no
Repayment method
differential, annuity
Frequency of payments
monthly
Borrower requirements
1. As of the operational reporting date, the Borrower’s financial results, as reflected in the Statement of Financial Results (Form No. 2), must not indicate a loss, except in cases where the negative financial results are substantiated by reliable data. 2. As of the operational reporting date, the Borrower’s own working capital must not be negative, except in cases where the relevant figure is substantiated by reliable data. 3. The Borrower must have no overdue debt under existing loans or transactions equivalent to loans. 4. Over the preceding 12 months, the Borrower’s credit history must meet the following requirements: - No more than two instances of overdue debt exceeding 30 days (30+); - No more than one instance of overdue debt exceeding 60 days (60+); - No instances of overdue debt exceeding 90 days (90+). 5. No overdue loan debt must exist within the JSCB “Asia Alliance Bank” system in respect of related entities under the Borrower’s control. 6. According to the Borrower’s credit history report issued by KATM, the client must have no outstanding loans classified as “unsatisfactory,” “doubtful,” or “loss” at any commercial bank. The same requirement applies to the Borrower’s related entities within the JSCB “Asia Alliance Bank” system. 7. There must be no instances of extension of interim or final repayment deadlines for principal or accrued interest on the Borrower’s existing loans within the JSCB “Asia Alliance Bank” system. 8. There must be no instances of failure by the Borrower to comply with the terms and conditions established by the Bank’s collegial decision-making body in respect of existing loans and outstanding obligations within the JSCB “Asia Alliance Bank” system, including non-fulfilment of obligations or failure to fulfil them within the prescribed time limits. 9. There must be no instances of misuse of loan proceeds under the Borrower’s existing loans within the JSCB “Asia Alliance Bank” system. Verification of the intended use of loan proceeds shall be carried out on the basis of a report confirming the intended use of the funds. This requirement shall not apply to loans for which the deadline for preparing such a report has not yet arrived; cases where the client has initiated legal proceedings against a supplier due to non-delivery of goods or non-provision of services; or loans issued for products for which verification of the intended use of funds is not required. 10. The client must have no outstanding amounts payable under enforcement proceedings initiated against the client by the Bureau of Compulsory Enforcement. 11. If, during the preceding three years, lawsuits concerning credit services have been filed with an economic court and such claims have been satisfied in whole or in part, the application shall be reviewed and rejected.
Loan Provision Order
Repayment of the loan principal and accrued interest shall be made in accordance with the procedure and terms stipulated in the loan agreement, using either the annuity or differentiated repayment method.
Required Documents
- Documents Required from Legal Entities: 1. Loan application, incorporation documents, information about the company’s founders and management, as well as the founders’ consent/resolution to obtain the loan and/or provide collateral. 2. Financial statements and related information (operational Forms No. 1 and No. 2), breakdowns of balance sheet items, information on turnover in bank accounts held with other banks, existing obligations, and other relevant information. 3. Calculations prepared by the client to substantiate the repayment of the loan, including project parameters and projected cash flows. 4. Documents relating to loan collateral. 5. Other documents related to the implementation of the project. - Documents Required from Individual Entrepreneurs: 1. Loan application, state registration certificate, copy of passport, and documents confirming the place of business. 2. Calculations prepared by the client to substantiate the repayment of the loan, including projected cash flows, as well as other documents related to the implementation of the project. 3. Calculations prepared by the client to substantiate the repayment of the loan, including project parameters and projected cash flows. 4. Documents relating to loan collateral. 5. Other documents related to the implementation of the project.
Loan Service Fee
not required
Additional Conditions
1. If the NPL ratio for this modular loan exceeds 4% of the outstanding balance of the relevant product as of the reporting date, lending shall be suspended. Information on the NPL ratio as of the reporting date shall be provided by the relevant department of the Bank. Lending shall resume once the NPL ratio falls below the established threshold. 2. The intended use of the loan proceeds shall not be subject to verification. The provision of the asset acquired with the loan proceeds as collateral shall, in itself, constitute sufficient grounds for granting the loan.
Early repayment
possibly
Limit increase
not provided
Early limit closure
not provided
Loan terms and interest rates:
|
The amount of the initial payment (Regarding the price specified in the vehicle supply contract) |
Loan period / Interest rate | |||||
| 12 month | 18 month | 24 month | 36 month | 48 month | 60 month | |
| From 25% | 0,00% | 6,00% | 10,00% | 15,50% | 17,50% | 19,00% |
| From 30% | 0,00% | 4,50% | 9,00% | 14,50% | 17,00% | 18,50% |
| From 40% | 0,00% | 0,00% | 6,50% | 13,00% | 16,00% | 17,50% |
| From 50% | 0,00% | 0,00% | 3,50% | 11,00% | 14,50% | 16,00% |
| From 60% | 0,00% | 0,00% | 0,00% | 7,50% | 12,00% | 14,50% |
| From 70% | 0,00% | 0,00% | 0,00% | 1,50% | 7,50% | 11,00% |
We are happy to help you
Our consultants will help you solve any issue. Just give us a call or request a call back.
If you have questions about deposits, our consultants will answer them.
Contact center
Work schedule: 24/7
The Alliance Pay mobile application is equipped with interactive services and a calculator.
An online chat with the Bank's Support Service is also available.
Other loans
YOSHLAR TADBIRKORLIGI
-
Interest rateCentral Bank Base Rate + 8%
-
Credit termup to 60 months
BUSINESS LIMIT
-
Interest ratefrom 23% to 25% per annum
-
Credit termup to 12 months
BIZNES STANDART
-
Interest ratefrom 21% to 24% per annum (in UZS), from 13% to 16% per annum (in USD), from 10% to 12% per annum (EUR)
-
Credit termup to 60 months
LOANS LIMIT
-
Interest ratefrom 21% to 26% per annum (in UZS), from 12,5% to 14% per annum (in USD), from 10% to 12% per annum (EUR)
-
Credit termup to 60 months
BIZNES OVERDRAFT
-
Interest ratefrom 21,99% to 25,99% per annum (in UZS), from 14,5% to 15,5% per annum (in USD), from 10% to 12% per annum (EUR)
-
Credit termup to 36 months
BIZNES IPOTEKA
-
Interest ratefrom 22,99% to 26,99% per annum (in UZS), from 13,5% to 15,5% per annum (in USD), from 11% to 13% per annum (EUR)
-
Credit termup to 84 months
UNIVERSAL ECO AUTO
-
Interest ratefrom 21% to 25% per annum (in UZS), from 13,5% to 14% per annum (in USD)
-
Credit termup to 60 months
BANDLIKKA KO'MAK
-
Interest ratefrom 23% to 24% per annum (in UZS), from 12% to 13% per annum (in USD)
-
Credit termup to 36 months
YANGI TADBIRKOR
-
Interest ratefrom 21% to 24% per annum (in UZS), from 12% to 14% per annum (in USD)
-
Credit termup to 24 months
YASHIL IQTISODIYOT
-
Interest rateCentral Bank of Uzbekistan base rate + 7%
-
Credit termfrom 60 months